Oct 28 - buy reported - terms undisclosed - renting since 2025 - OCI carries TPUs 2027
The decision · Price a second accelerator into your next procurement round before Q1 budgets lock. If your workloads are mostly inference, ask your provider for its multi-vendor roadmap by December 15, because porting work takes months and the largest GPU buyer in the market just told everyone it wants an alternative.
Oct 26 - ~$40B master financing - Apollo - Vera Rubin GPUs - largest GPU financing on record
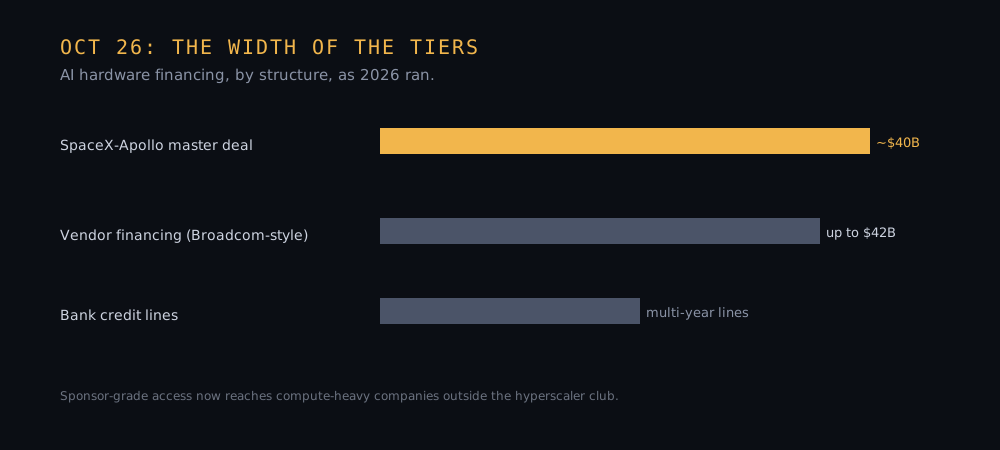
The decision · Re-price your large GPU financing against this deal before your own capital committee meets. If you lease AI compute, ask whether sponsor-class financing reaches your volume, because the credit ladder set its widest rung this week. If you carry AI hardware debt, price a second source: sponsor spreads price the hardware as the asset, and your residual value carries the same base.
Oct 21 - GPT-6 models in Model Garden - beyond Microsoft - one cloud, three labs - routing in one perimeter
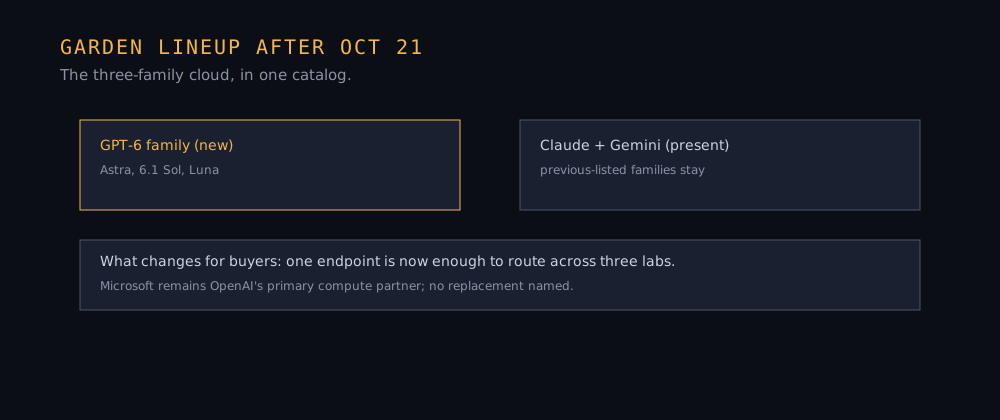
The decision · Re-quote your cloud inference contracts before the ends of renewals, now that GPT-6 lists inside Model Garden. If you run multi-cloud routing, price Model Garden against your current router stack by December 1, and keep one fallback endpoint outside Google, because the garden sets both the convenience and the dependency.
Oct 15 - Super VL 120B open - Bolt 74B in 24GB - 2-bit native - E4B 4GB variant Oct 23
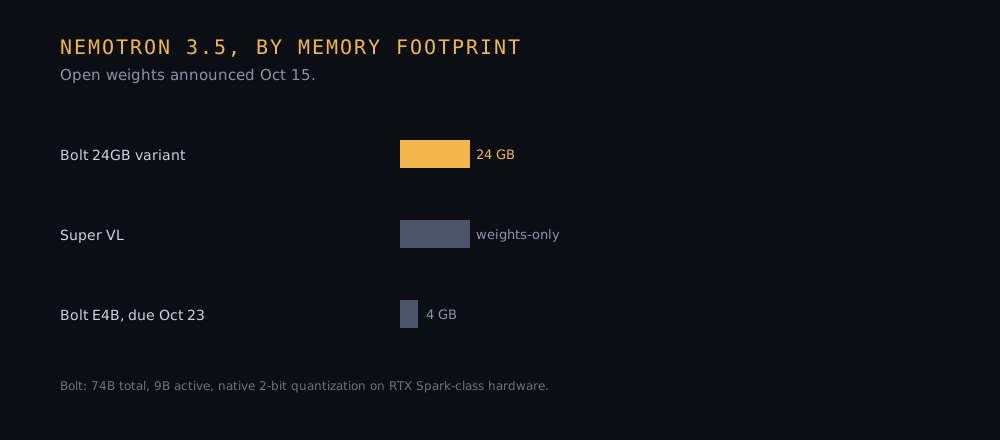
The decision · Test SaaS agents against a local Nemotron 3.5 Bolt instance on one workload by October 23, when the 4GB variant ships. If the 2-bit quality holds on your workload, add a local tier to your function and route cost-tier agent traffic to hardware you control, while the API bills only the quality-tier calls.
Oct 3 - up to $42B loan - third of $125.2B TPU leases - in the IPO filing - vendor financing
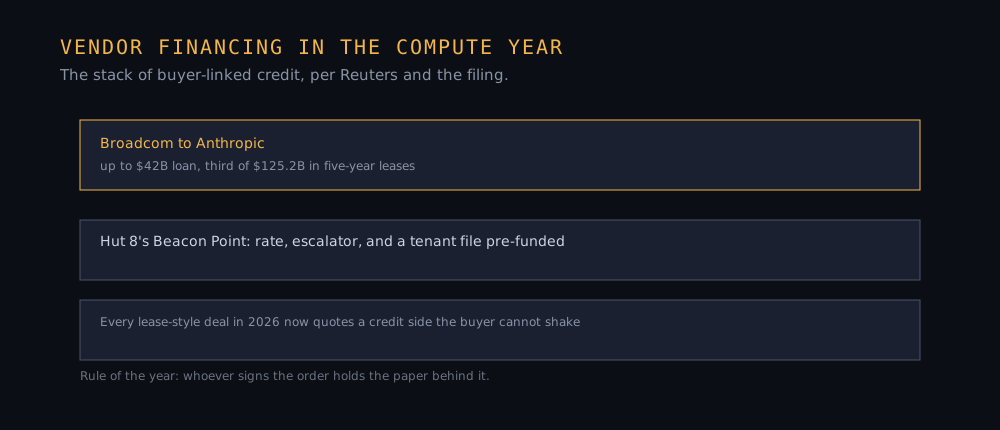
The decision · Re-read your compute supplier's credit posture before your next large lease, because suppliers are lending now. If you lease chips, ask whether your vendor offers financing and on what terms, and run one comparison against a bank loan before committing. Do the math by October 31, because vendor credit prices customer risk, and the risk shares a line item with your own renewal.
Sep 24 - TPU prototype announced for orbit - Transporter-18, Planet Labs - four TPUs due Oct 1 - year-long trial
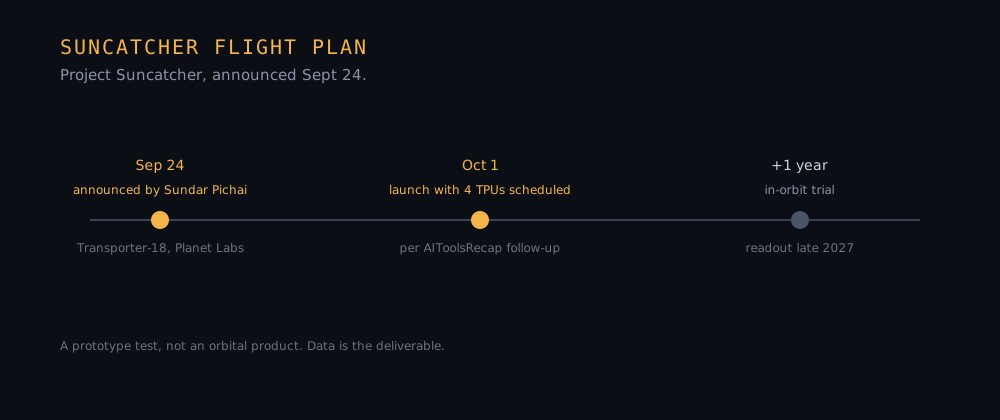
The decision · Watch the actual launch window for your own AI hardware plans, not just the announcement cycle. If your team builds any satellite-linked compute, request the radiation and thermal readout from Suncatcher's one-year data before you commit hardware. If you price compute capacity, treat orbital compute as a research product for now, with no procurement decision before that data lands in late 2027.
Sep 14 - Micron, Intel, Marvell, AMAT -4%+ - Nvidia -3% - SK Hynix -7% - cyber stocks +13%
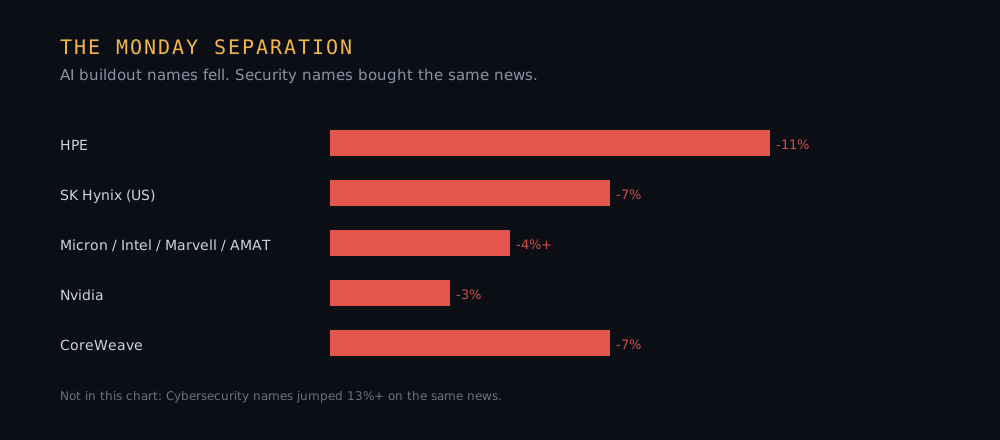
The decision · Re-read your contract terms before you price new AI infrastructure purchases, and write the pace question in. If you lease or buy capacity, ask your vendor to scope a 12-month spend window with a safety-gate clause, so a slowdown decision does not strand your order. Set your next capex review for October 1, after the labs' replies to public calls have cleared.
Sep 7 - EUR 13B over 2027-2028 - up to half one nuclear plant - Hamina, Muhos, Vaala, Kajaani - first non-US nuclear agreement
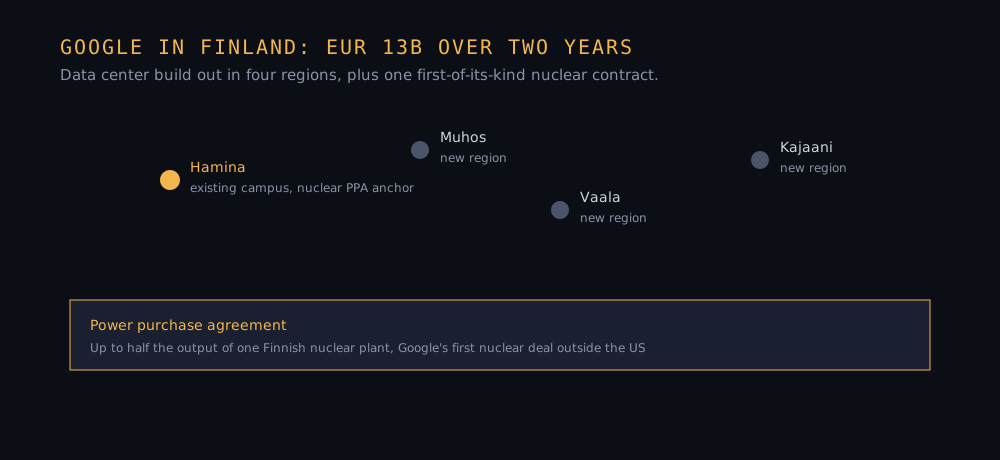
The decision · Re-price your own compute capacity search against firm-power contracts before the next European site closes. If you buy AI compute from a hyperscaler, ask which region the workload lands in and whether its grid has firm baseload, because a cheaper cloud region without firm power now means the latency and cost of a queue you cannot shorten. Set your first Nordic capacity review before end of 2027, when the first Google phase lands.
Sep 6 - 160,000 Ascend 950DT - 1 GW Ulanqab - ~$2.56B order - inference only - online end-2027
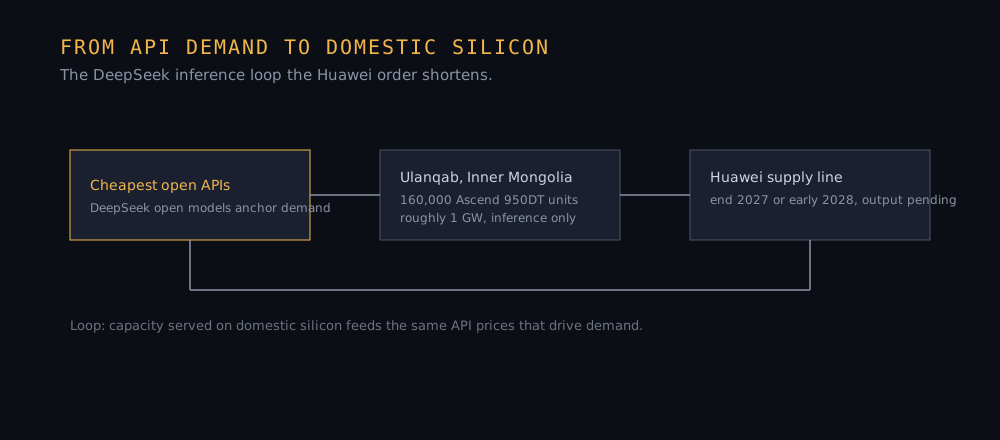
The decision · Re-quote your Chinese inference API spend before the Ulanqab capacity goes online. If DeepSeek serves more of its API load on Huawei silicon from late 2027, pricing falls with it. Set a review for December 2027 to re-price any Chinese-lab API renewal against that capacity, and hold off on Nvidia-dependent inference expansions in codebases you rent capacity for.
Aug 31 - $35B - ~350MW - 6 years - rent $1.86M/MW/yr - Nvidia holds the lease
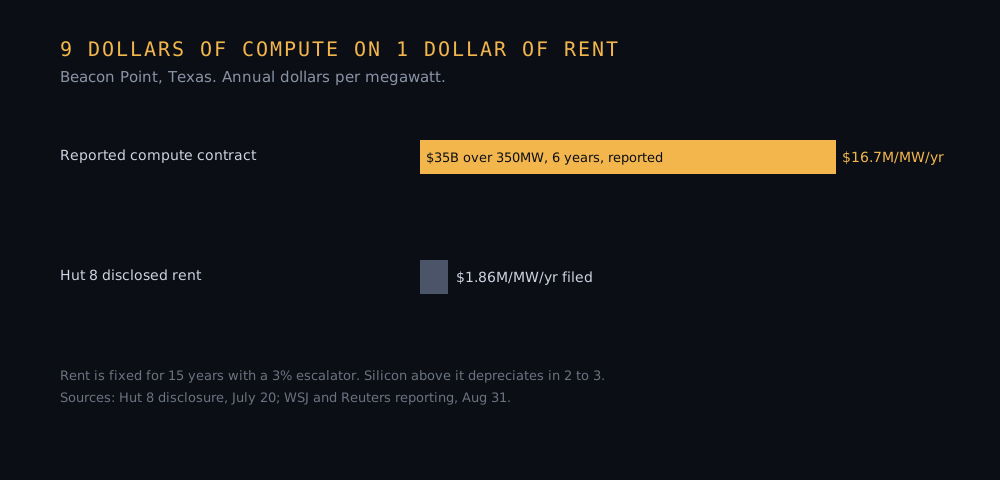
The decision · Re-price your own capacity negotiations against the disclosed $1.86 million per megawatt benchmark before the next campus closes. Treat the $35 billion headline as a demand signal, hold those talks under fifteen years if you sit on the rent side, and if you buy compute from Anthropic, confirm delivery dates that survive 2027 energization before you sign anything this quarter.