Nov 2 - Musk on X - cost vs revenue gap - no figures given - caps unpublished
The decision · Measure your agent's cost per heavy user before your next renewal or pricing meeting, and do it by November 15. Export last week's token totals, count the share eaten by context re-reads, and decide whether your flat price survives a week where the largest agent sellers just admitted theirs did not.
Oct 31 - $20B target - $1.25T post-money - from $30B at $1.4T - first close may fall short
The decision · Re-price your own raise this week against a market that just cut its largest AI round by a third. If your deck still quotes multiples from September, rewrite them before your next investor meeting, because $1.25 trillion is now the reference every private AI investor will open with.
Oct 26 - $16.3B H1 revenue - $693M operating loss - ANT on Nasdaq - price not set
The decision · Re-negotiate your Anthropic contract before the company starts pitching investors in about two weeks. The filing shows existing customers paying roughly nine times what they paid a year ago. Public growth targets will push account teams to expand your spend this quarter. Lock a 12-month rate by November 10, or change your AI budget for 2027 before a price appears.
Oct 22 - capex $135B to $145B - Meta -7% - Nasdaq -2.6% - AI buildout repriced
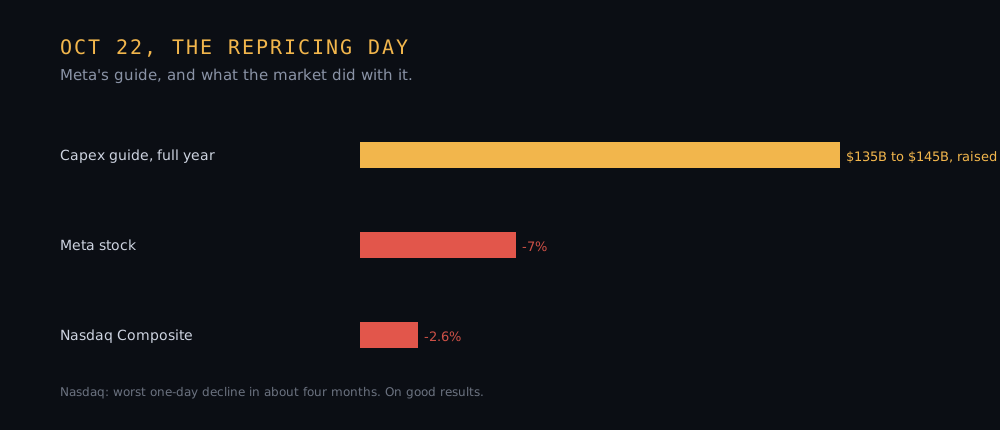
The decision · Re-negotiate your cloud-and-capacity contracts before December 1, on the week's move. Ask each provider to price capacity in a new guide range for your spend, since hyperscaler cost models just moved and buyers hold more leverage today than they did last week. And for any AI-linked stock in your portfolio, re-read the credit line: CDS moves say more than the capex headline.
Oct 19 - ~$30B raise - above $1.4T - ahead of Anthropic IPO - Reuters report
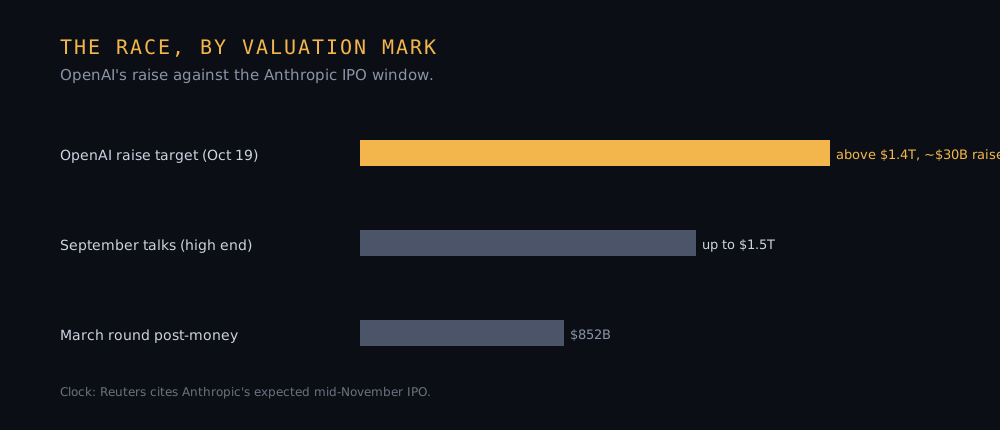
The decision · Build your two-column view of the frontier before November 30, one private and one public. If you sell into both labs, price urgency into the private side before the raise closes, because contracts signed during a funding window carry different renewal leverage. If you invest, treat the no-disclosure discount as a real cost, not a rounding note.
Oct 14 - $750M Series D - Accel lead, Kleiner in - $15.75B post-money - >$1B ARR
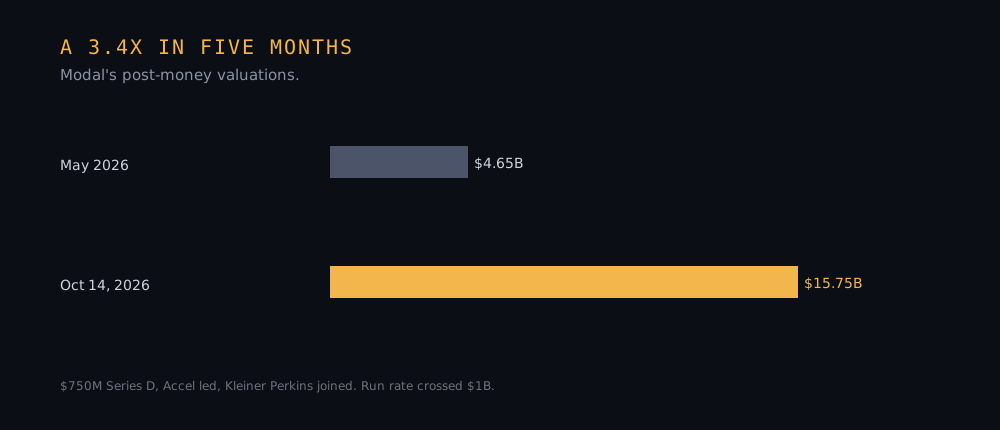
The decision · Re-price your burst compute needs by November 1. Any agent fleet that runs bursty inflow, cold starts, or short tools should be quoted both ways: reserved cluster versus serverless GPU. If your utilization sits under 60 percent, serverless is a cost posture, not a vendor choice.
Oct 9 - up to $100B target - Gulf investors incl UAE - buys incumbents, applies AI - follows $30B OpenAI bet
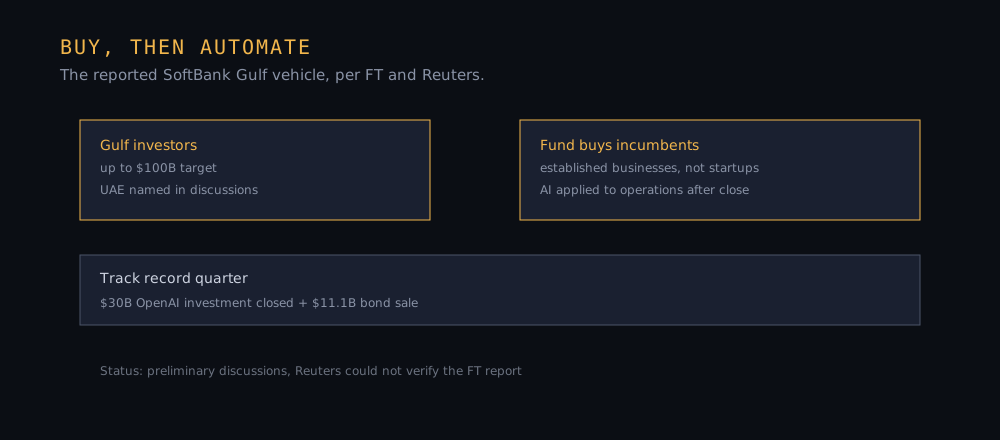
The decision · Map your own portfolio for an AI-operator offer before this fund closes. If you own an operating company, model what an AI-enabled operator cohort would pay versus your private-market alternatives. Set that analysis inside your next board budget by December 1, because a fund of this size bids first where incumbent revenue runs predictable.
Sep 28 - $8.2B all-stock - Li joins AMD as EVIP + chief scientist - chipmaker buys a model lab - Nvidia gets a second rival axis
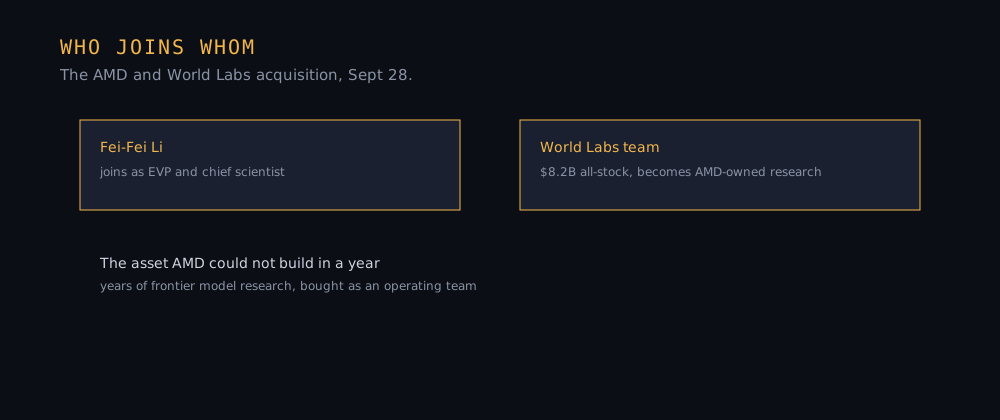
The decision · Re-rate AMD and World Labs' product momentum against Nvidia by your next AI hardware renewal. If you lease AMD compute, the research bundle strengthens the value case by one front. If you run Nvidia-only procurement, your second-source argument just grew: an owned model-lab research asset is the pattern competitive chip vendors will imitate by early 2027.
Sep 16 - $1.2T to 1.5T talks - up from $852B March - run rate >$40B - IPO slips to 2027
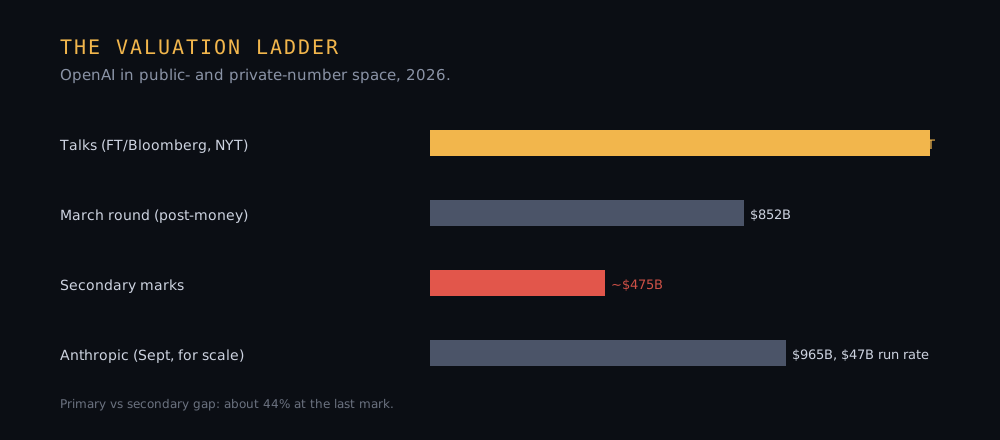
The decision · Update your valuation comps for both frontier labs by September 30. If you buy from OpenAI, use the talks to negotiate: a company raising $1.2 trillion prices service commitments differently when every contract influences its IPO narrative. If you invest privately, price the secondary discount, roughly 44 percent at the last mark, as a real cost rather than a rounding error.
Sep 8 - EUR 3B Series D - >EUR 21B post-money - Samsung-led - Nvidia + ASML co-backers
The decision · Re-underwrite your European AI vendor short list by September 22, when the round closes. Institutional buyers in regulated sectors now have a defensible non-American supplier at a $24.39 billion scale. Run a two-vendor comparison against an American frontier lab for your next procurement, and weigh the data-residency premium against the frontier gap before you sign either.